Daily Global Market Overview By zForex

Fed Hike Bets Push Metals to 7 Week Lows (09.28.2026)​

Gold fell below $4,250 to a seven-week low as stalled US-Iran talks kept oil prices high and reinforced inflation concerns. Several Fed officials pointed to resilient growth and a strong labor market as reasons for further hikes, while attention now moves to the Fed’s preferred inflation measure and key US jobs data.

Silver fell below $62 an ounce on Monday, approaching a seven-week low as stalled US-Iran negotiations sustained high oil prices and reinforced expectations of Federal Reserve rate hikes. President Donald Trump dismissed Iran's proposal to reopen the Strait of Hormuz, while Iranian officials refused to ease their stance.

The dollar stayed firm as expectations for further Fed tightening and high Treasury yields weighed on major currencies.

EUR/USD slipped to 1.1391, down 1.95% over the past month, while the yen weakened toward 158 per dollar despite growing speculation that the BOJ could hike again in October.

The yen weakened toward 158 per dollar, giving back some of Friday’s 1% gain as a firmer dollar, high Treasury yields and expectations for further Fed tightening weighed on the currency.

Sterling ticked slightly higher to $1.325 but remained near three-month lows as market participants evaluated hawkish rhetoric from Bank of England officials. Governor Andrew Bailey and monetary policy members warned that surging energy prices could force additional interest rate hikes to combat persistent inflation.

The offshore yuan weakened to around 6.72 per dollar, its fourth straight session of losses as traders assessed outcomes from the Trump-Xi summit in Washington.

Brent rebounded above $106 after Trump rejected Iran’s latest proposal to reopen the Strait of Hormuz. Tehran said it would not ease its conditions, leaving uncertainty over when oil flows through the waterway could fully resume.

The Nasdaq 100 traded at 30,392, up 0.42% from the previous session. Trading Economics' global macro models and analyst estimates project the index at 29,947 by quarter-end and 28,048 in a year.

Check more on zForex.com | Technical Outlook on Charts​


High Yields and Fed Pressure Metals (09.29.2026)​

Renewed Middle East tensions and persistent inflation concerns are keeping financial conditions tight on September 29. The dollar remains near a two-month high as markets price roughly a two-thirds chance of another Federal Reserve rate hike in October. Rising oil prices and elevated Treasury yields are reinforcing expectations that monetary policy may need to stay restrictive for longer.

Economic Calendar​

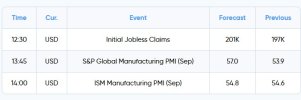
eco-cal-29-sep.jpg


EUR/USD has fallen toward 1.136, its weakest level since late July. The ECB’s recent rate increase has provided limited support as the widening US yield advantage continues to favor the dollar. Attention now turns to German inflation and retail sales data for further clues on the European outlook.

Energy markets have again become the main geopolitical risk. Oil rose for a second session after Washington rejected Iran’s latest proposal concerning the Strait of Hormuz, while continued regional tensions threaten supply routes.

Brent’s November contract moved above $106, although later-dated prices remain lower, reflecting uncertainty over how long disruptions will persist.

Gold is attempting to recover after falling to a seven-week low, trading near $4,144 as higher yields and Fed tightening expectations offset demand for geopolitical protection.

Silver stabilized around $60.8 per ounce on Tuesday following a nearly 6% slide in the prior session. Oil prices climbed as Iranian officials expressed doubt over securing a deal before the US midterm elections after President Donald Trump rejected Tehran's latest proposal.

USD/JPY has eased toward 157 as speculation grows that the BoJ could tighten again, although the broader dollar backdrop remains supportive. Meanwhile, US technology shares have weakened as higher yields pressure valuations, while Bitcoin remains near $83,000.

GBP/USD edged up to around $1.3251 on Tuesday, recovering slightly after an extended slide left its 14-day RSI oversold near 30. Bank of England officials delivered hawkish signals, with Deputy Governor Ramsden and Governor Bailey pointing to persistent inflation and energy costs as reasons further rate hikes remain possible.

In China, sentiment received modest support from targeted US-China tariff reductions following the Trump-Xi summit, but major disagreements remain unresolved. China is also preparing additional economic support as domestic growth pressures persist.

The offshore yuan strengthened to around 6.70 per dollar, extending gains as markets assessed the Trump-Xi summit. The US and China agreed to reduce tariffs on about $30 billion of imports from each country and extend their trade truce through January.

Check more on zForex.com | Technical Outlook on Charts​


Dollar Strength Pressures Markets (09.30.2026)​


Economic Calendar

eco-cal-30-sept.jpg


EURUSD​

The euro fell to approximately $1.133, hitting its lowest level since May 2025, pressured by a strengthening US dollar and policy divergence expectations between central banks. Higher oil prices driven by stalled Hormuz negotiations have fueled bets on Federal Reserve tightening. Meanwhile, ECB President Christine Lagarde signaled a measured stance, noting limited second-round inflation effects. Despite sluggish European growth projections and upcoming political uncertainty, elevated inflation keeps four ECB rate hikes priced in over the coming year.

GOLD​

Gold stabilized near $4,180 per ounce following a previous session rebound, drawing support from easing crude oil prices. Upside remains constrained by elevated Treasury yields, with the 30-year rate hitting 5.62%, its highest level since June 2002. Persistent inflation concerns and hawkish Federal Reserve rhetoric continue to weigh on non-yielding assets, with New York Fed President John Williams suggesting a potential late-year rate hike. Gold remains set for a nearly 6% decline in September.

YEN​

Japanese officials warned against rapid currency movements and confirmed joint coordination with the United States, helping the yen firm past 157 per dollar. Nevertheless, substantial interest rate differentials between the US and Japan continue to exert persistent downward pressure on the currency.

STERLING​

Sterling fell toward $1.32, hovering near a three-month low, as expectations build for an October Federal Reserve interest rate hike while the Bank of England is projected to wait until November. Although markets price an 80% chance of a November BoE increase from its current 3.75% rate, sluggish UK economic growth may restrict additional monetary tightening.

SILVER​

Silver stabilized above $61 per ounce, snapping its recent slide as easing crude oil prices provided underlying support. However, high Treasury yields and hawkish Federal Reserve commentary continue to create strong headwinds, leaving the metal on track for a nearly 8% monthly decline.

BRENT​

Brent held near $96 after a sharp decline as Middle East exports recovered to 98% of pre-war levels and the US prepared to release up to 40 million barrels from its reserves. Saudi Arabia’s East-West pipeline is operating at around half capacity, while US crude inventories increased by 1 million barrels. Despite the pullback, Brent is heading for a third consecutive monthly gain, reflecting the impact of the US-Iran conflict on oil prices throughout the period.

NASDAQ 100​

The US 100 Tech Index rose 0.21% to 30,345, taking its four-week gain to 3.01% and its 12-month advance to 22.35%. Analysts predict the index to be at 29,947 by quarter-end and 28,048 in 12 months.

USD/CNH​

The yuan held near 6.70 per dollar after China’s Composite PMI climbed to 50.7, its highest since December 2025, alongside the announcement of new stimulus measures. The currency is also on track for its seventh consecutive quarterly gain.

BTC/USD​

Bitcoin slipped 0.38% to $83,313, extending its monthly decline to around 6%, while losses over the past year approach 30%. Trading Economics forecasts the cryptocurrency at $84,180 by quarter-end and $95,059 in 12 months.

Check more on zForex.com | Technical Outlook on Charts​


Softer US Inflation Offers Limited Relief (10.01.2026)​

Economic Calendar
eco-calendar-1-oct.jpg
EUR/USD

The euro remained under pressure as accelerating inflation across major European economies contrasted with rising US Treasury yields that continue supporting the dollar. EUR/USD closed below 1.1350 for a second straight session after Spain’s annual inflation rate reached 5% in September, its highest mark since 2023. Financial markets now await Friday's preliminary eurozone inflation data, where headline consumer price growth is projected to pick up to 3.6%.

Gold
Gold advanced toward $4,200 per ounce on Thursday, rebounding after cooler US PCE inflation data reduced market expectations for an October Federal Reserve rate hike to 38%. Easing crude oil prices also lent support amid signs of improving Middle East energy supply. However, elevated Treasury yields near multi-decade highs continue to limit broader gains, with markets still pricing in a 97% probability of a Fed rate increase in December.

Japanese Yen
Japan’s S&P Global Manufacturing PMI was finalized at 54.1 for September 2026, dropping from August's 54.9 reading to mark the slowest pace of expansion since March amid moderating output and new orders. Following the release, USD/JPY tested above 158.00, with technical analysts noting that a decisive break past 158.28 could clear the path toward 159.00 and 161.10.

GBP/USD
GBP/USD weakened to around 1.3265 in early European trading on Thursday, remaining under downward pressure below its 100-day SMA. Despite deeply oversold conditions, the technical outlook favors further weakness. Key technical levels highlight initial resistance around 1.3260, with immediate support resting at 1.3200 on the downside.

Silver
Silver traded near $61 per ounce on Thursday, touching a two-month low as high Treasury yields and elevated energy costs overshadowed softer US inflation figures. August PCE data showed headline inflation slowing to 3.4% year-over-year, undercutting expectations and lowering the market-implied probability of an October Federal Reserve rate hike to roughly 38%. However, persistent crude oil strength linked to slow progress in US-Iran negotiations continues to weigh on precious metal sentiment.

BTCUSD
Bitcoin traded near $83,481, down 0.07% on the day. The cryptocurrency has lost 8.01% over the past four weeks and 30.83% over the past year, while analysts project $84,180 by quarter-end and $95,059 within 12 months.

BRENT OIL
Brent held near $98 as recovering Middle East supply competed with the ongoing deadlock in US-Iran talks. Regional shipments are approaching pre-war levels after Saudi Arabia restored half the capacity of its East-West pipeline, while flows through the Strait of Hormuz reached 13.2 million barrels per day. The recovery remains vulnerable without a lasting agreement to end the Iran war, with Tehran and Washington both claiming control of the strategic waterway.

NASDAQ 100
The US 100 Tech Index rose 0.23% to 30,561, extending its four-week gain to 4.87% and its 12-month advance to 22.77%. Trading Economics projects the index at 29,947 by quarter-end and 28,048 within a year.

USDCNH
The Offshore Chinese Yuan held near 6.70 per dollar as stronger activity data and additional policy support improved sentiment around China’s economy. The official Composite PMI rose to 50.7, its highest since December 2025, with manufacturing returning to expansion at 50.1 from 49.8 and non-manufacturing climbing to 50.2 from 49.0. Private data painted an even stronger picture: the Composite PMI reached 52.1, manufacturing rose to 52.1 from 51.5, and services edged up to 51.6 from 51.4.
 

Strong Dollar Continues to Weigh on Markets (10.02.2026)​


A stronger dollar and elevated Treasury yields kept pressure on major currencies and precious metals as markets awaited the latest US employment data.

Economic Calendar​

eco-cal-2-oct.jpg

EURUSD​

The euro fell below $1.13 to hit its lowest level since May 2025, following a September slide of over 2%, its sharpest monthly drop in 14 months. Broad dollar strength and expectations that the European Central Bank will lag the Federal Reserve's tightening pace weighed heavily.

JAPANESE YEN​

The yen firmed slightly below 158 per dollar on Friday as Tokyo’s core inflation rate accelerated to 2.7% in September, surpassing the Bank of Japan’s 2% target for the first time in nine months.

BRITISH POUND​

Sterling weakened to around $1.32 near three-month lows at the start of October, following a 2% September drop as elevated oil prices heightened inflation concerns, raised bond yields, and dampened economic growth prospects.

OFFSHORE CHINESE YUAN​

The offshore yuan weakened toward 6.71 per dollar as rising US Treasury yields supported the dollar, with higher oil prices adding to inflation concerns.

GOLD​

Gold slipped to around $4,190 an ounce on Friday, heading for a second consecutive weekly loss as rising crude oil prices driven by US-Iran geopolitical tension heightened inflation fears.

SILVER​

Silver hovered around $61.4 per ounce on Friday, bound for another weekly decline as rising crude oil prices sparked US-Iran escalation fears and renewed inflation worries.


BRENT OIL​

Brent climbed above $102 for a second day as possible US military reinforcements raised concerns over a wider conflict with Iran and fresh supply disruptions.

NASDAQ 100​

The US 100 Tech Index rose 0.31% to 30,617, bringing its four-week gain to 3.85% and its 12-month advance to 23.53%.
Trading Economics projects the index at 29,947 by quarter-end and 28,048 in 12 months.

BITCOIN​

Bitcoin edged 0.08% higher to $84,914, taking its four-week gain to 4.49%, though it remains 30.56% lower over the past year.
Trading Economics projects Bitcoin at $84,180 by quarter-end and $95,059 in 12 months.
 

US Payrolls Miss Forecasts as Hiring Slows​

US-Payrolls.jpg

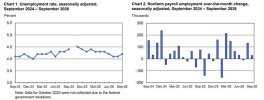
US payrolls rose by just 29,000 in September, well below expectations near 95,000, while previous months were revised lower. The three-month average fell to around 51,000, pointing to a clear slowdown in hiring, with wage growth also cooling to 0.1% month-on-month.

The unemployment rate edged up to 4.2%, although participation increased to 61.8%, suggesting more people returned to the labor force. Overall, the report points to a cooling labor market rather than a sharp deterioration.

For the Fed, weaker hiring and softer wage pressures could reduce the urgency for another near-term rate hike. Attention now shifts more heavily toward upcoming inflation data for the next policy signal.
 

Safe-Haven Demand Keeps Dollar Firm (10.05.2026)​

US equity futures extended Friday’s gains as weak jobs data reduced expectations for further Fed hikes. Nasdaq 100 futures rose 0.3%, while Dow and S&P 500 contracts added 0.1%, with ISM services, Fed minutes and earnings from PepsiCo and Delta next in focus.

Treasury yields eased but stayed near two-decade highs, with the 10-year around 5.25% and 30-year near 5.6%. September payrolls rose just 29K, unemployment reached 4.2% and wage growth slowed, though energy-driven inflation, fiscal concerns and AI-related borrowing kept yields high.

The dollar index held near 102, close to its strongest since April 2025. Fading Fed hike bets limited gains, while euro weakness linked to French fiscal and political concerns provided support.

Japan’s Nikkei 225 jumped more than 2% toward 70,000, reaching a three-month high as softer US jobs data lifted technology and AI shares. Advantest, SoftBank Group and Tokyo Electron gained over 3%, though high bond yields and Middle East risks kept caution in place.

Economic Calendar​

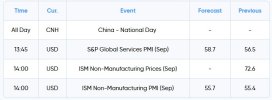
eco-calendar-5-oct.jpg
  • EUR/USD fell 0.71% to 1.1174 in early Monday trade as safe-haven flows, rising Treasury yields and concerns over France’s fiscal outlook favored the dollar.
  • The yen held near 157.8 per dollar, extending its two-week sideways move before Japanese wage, household spending and consumer confidence data.
  • Sterling weakened on Monday but held above $1.32 as broad US dollar firmness counteracted soft US labor data. Downside stayed contained as markets continue pricing roughly 30 basis points of Bank of England tightening by year-end amid energy-led inflation risks.
  • The offshore yuan weakened toward 6.71 per dollar, reversing last week’s gains as dollar strength spilled across currencies.
  • Gold traded near $4,140, recovering part of Friday’s decline after September payrolls rose just 29,000, unemployment increased to 4.2% and wage growth slowed.
  • Silver climbed above $61 per ounce on Monday, recovering from earlier losses as weak US employment figures reduced Federal Reserve rate-hike prospects. September non-farm payrolls added only 29K jobs, while unemployment ticked up to 4.2% and wage growth moderated.
  • Bitcoin traded near $86,400, consolidating below its recent intraday high after entering October with positive momentum following a rare September gain.
  • Brent fell below $101.30 as Saudi-backed forces launched a major operation against the Houthis, who seized the Bab el-Mandeb chokepoint used for Saudi oil exports.
  • The Nasdaq-100 traded near 30,808 after gaining 1% in its latest session, with futures adding around 0.3%. Weak payrolls and slower wage growth strengthened expectations for a Fed pause, supporting tech stocks, while strong chipmaker performance helped offset high Treasury yields.

Check more on zForex.com | Technical Outlook on Charts​