Daily Global Market Overview By zForex

Rising Oil Prices Reinforce Rate Hike Bets (09.01.2026)

The US 10-year yield climbed to 4.78%, its highest since January 2025, as higher oil prices and hawkish Fed signals pushed September hike odds above 65% from 36%. Warsh said the Fed “will have work to do” without clearer inflation progress.

US stock futures steadied after Monday’s losses as higher oil prices fueled inflation concerns and lifted Treasury yields. The Dow fell 0.7%, while the S&P 500 and Nasdaq lost 0.33% and 0.12%. Manufacturing and services data come next, followed by Friday’s jobs report.

Japan’s 10-year yield jumped to 2.99%, its highest since 1996, as yen weakness and import-driven inflation strengthened BOJ hike expectations. Bessent reportedly urged Katayama and Ueda to raise rates, while higher US yields added pressure.

The Dollar Index steadied near 99.5 as Warsh’s hawkish remarks and rising oil prices strengthened Fed hike expectations. Oil gained for a second day following US strikes on Hormuz and Iranian retaliation against the UAE and Jordan.

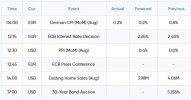
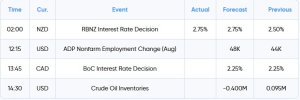
Economic Calendar​

eco-calendar-1-september.jpg
  • The euro traded near $1.16, close to a two-week low, as higher oil prices strengthened rate-hike expectations in both the Eurozone and US. Oil rose following US strikes on an Iranian island in Hormuz and Iran’s retaliation against US assets.
  • The yen traded near 159.8 per dollar, attempting to recover after approaching the key 160 level and reviving intervention concerns. It has erased more than half of its gains following July’s joint Japan-US intervention, pressured by wide rate differentials, fiscal concerns and higher oil prices.
  • The British pound slipped toward $1.35, hitting its lowest point since August 19. Hawkish comments from Kevin Warsh strengthened the dollar by warning that US inflation remains persistent.
  • The offshore yuan strengthened to around 6.72 per dollar despite data showing persistent weakness in China’s economy. The Composite PMI edged up to 49.5 in August from 49.3, while manufacturing and services remained in contraction and industrial profit growth slowed to 17.6%.
  • Gold slipped below $4,450, trading near two-week lows as rising oil prices and hawkish comments from Fed Chair Warsh pushed September hike odds above 65% from 36%.
  • Silver dipped near two-week lows around $66.5 on Tuesday as surging oil prices and hawkish Fed comments raised September rate-hike expectations past 65%, escalating Middle East conflicts drove energy costs higher.
  • Brent climbed toward $91 as fresh US-Iran hostilities increased the risk of further energy disruptions. US forces struck Iranian rocket launchers on Larak Island, followed by Iranian retaliation against the UAE and Jordan, while Trump extended threats to Kharg Island.
  • Bitcoin traded near $78,742, pulling back from its recent high of $81,350 as hawkish Fed expectations triggered profit-taking.
  • The Nasdaq 100 traded roughly flat near 29,457. Warsh’s comments lifted September hike odds to 59.7%, while higher Treasury yields and a stronger dollar limited tech gains.
Check more on zForex.com | Technical Outlook on Charts


Rising Yields Pressure Global Markets (09.02.2026)

The 10-year Treasury yield climbed above 4.8%, approaching its highest since October 2023, as rising oil prices lifted inflation concerns and September Fed hike odds to around 70%. Oil gained for a third session as US-Iran hostilities intensified, while Barr reinforced the case for further tightening if inflation persists.

US stock futures steadied after a third straight decline, with the Dow down 0.79%, S&P 500 0.71%, and Nasdaq 1.03% on Tuesday. Rising oil and bond yields drove the pressure, while ADP, the Fed’s Beige Book, and earnings from Broadcom, HP, and Snowflake are next.

The Dollar Index climbed above 99.7, its highest in nearly three weeks, as surging oil prices pushed September Fed hike odds to around 70%. Fed Governor Barr said further hikes may be needed if inflation persists, with ADP and Friday’s jobs report next.

Japan’s 10-year yield topped 3% for the first time since 1996, driven by higher oil prices, BOJ hike expectations, and concerns over the Takaichi administration’s spending and tax-cut plans. Bessent also urged Ueda to take “decisive” steps against yen weakness.

Economic Calendar​


eco-calendar-2-september.jpg
  1. The euro slipped below $1.16 as traders assessed Eurozone inflation and the outlook for ECB policy. Annual inflation accelerated to 3.3% in August, the highest since September 2023, driven by higher energy prices linked to the Middle East conflict.
  2. The yen weakened past 160 per dollar, its lowest in a month, erasing roughly two-thirds of the gains following last month’s joint Japan-US intervention. Wide rate differentials, fiscal concerns, and high oil prices continued to weigh on the currency.
  3. GBP/USD fell to around $1.3496, extending its losses past the 1.3500 threshold as hawkish comments from Fed Chair Warsh drove broad dollar demand. Rising UK public sector borrowing added pressure on sterling, while strong US manufacturing PMI data carried expectations for elevated Fed interest rates, steering capital away from European currencies.
  4. USD/CNY traded near 6.7230, extending its decline as strong export settlement and corporate dollar selling supported the yuan. The PBOC set its official reference rate slightly higher to limit volatility while signaling comfort with further yuan appreciation.
  5. Gold fell toward $4,300, extending its decline to a fourth session and reaching its lowest level in more than three weeks. Higher bond yields, rising oil prices, and Warsh’s hawkish stance pushed September Fed hike odds to around 70%.
  6. Silver fell below $64 on Wednesday, extending losses as rising bond yields and energy costs drove up Fed rate-hike expectations. Hawkish comments from Kevin Warsh lifted September hike odds near 70%. Markets are now focused on upcoming US employment reports, while escalating US-Iran conflict continued to push oil prices higher.
  7. Bitcoin traded near $78,742, retreating from its recent $81,350 high as hawkish Fed expectations encouraged profit-taking. MicroStrategy added roughly 4,600 BTC, taking its total holdings to 845,050 BTC, while BlackRock’s spot Bitcoin ETF reached $98.6 billion in assets.
  8. Brent climbed above $95, rising for a third session to a six-week high as US-Iran hostilities increased the threat of energy disruptions. The US launched new strikes near Hormuz following Iranian mine-laying attempts and an attack on a base, while Trump threatened a larger response to further retaliation.
  9. The Nasdaq 100 fell 1.29% to 29,077, breaking below key support as global bond yields climbed and the US 10-year Treasury yield reached 4.79%. Brent’s rise above $92 added to inflation concerns, while Warsh’s hawkish comments strengthened September Fed hike expectations and pressured tech stocks.

Check more on zForex.com | Technical Outlook on Charts


Dovish Fed Lifts Metals as Dollar Pauses (09.04.2026)

The US 10-year yield eased to around 4.76% after reaching three-year highs as Waller said he would support holding rates if inflation keeps cooling. September hike odds dropped to roughly 50% from 63%. The jobs report is next, while oil heads for a strong weekly gain as Middle East tensions and Hormuz shipping uncertainty persist.

US stock futures held steady before the August jobs report after Thursday’s rally, when the Dow gained 1.18%, S&P 500 1.06%, and Nasdaq 1.4% as Treasury yields eased. DocuSign rose 4% postmarket on strong Q2 results and higher guidance, while Lululemon plunged 18% after weak sales and a disappointing outlook.

Japan’s 10-year yield fell to around 2.9% for a second session as the global bond selloff eased and a successful 30-year JGB auction drew pension-fund demand. Takata floated outsized or back-to-back hikes, while Ueda flagged upside inflation risks. A quarter-point hike this month and another in December are expected.

The Dollar Index held near 99 after a sharp decline, pressured by Waller’s dovish comments and a stronger yen as BOJ tightening expectations grew. With September hike odds down to 50% from 63%, the dollar is heading for a 0.7% weekly decline before the jobs report.

Economic Calendar​

eco-calendar-4-sept.jpg
  • The euro edged above $1.16, pausing its selloff as a yen rally weighed on the dollar and falling oil offered relief. Markets fully price in a 25bps ECB hike next week, with two more expected by mid-2027.
  • The yen held near 156 per dollar, extending gains for its strongest weekly performance (~2.5%) since July's joint intervention. Broad dollar weakness after Waller's dovish remarks also supported the yen.
  • GBP/USD rose toward 1.3530, recovering modestly from two-week lows. The pound drew support from BoE official Pill backing a rate increase to 4.00% and PM Burnham promising fiscal discipline. Meanwhile, the recent US dollar rally stalled as traders pause ahead of key US payrolls data to gauge the Fed's next policy moves.
  • Gold traded near $4,500, extending gains for a second session as dovish comments from Fed Governor Waller led markets to trim September hike bets to 50% from 63%. The dollar and yields fell sharply, supporting bullion, while oil headed for a strong weekly gain.
  • Silver climbed toward $67 on Friday, advancing for a second straight session after dovish remarks from Fed Governor Waller reduced September rate-hike expectations to 50%. Waller expressed support for holding interest rates steady if inflation continues to cool.
  • Bitcoin trades near $80,875, up 4.4% in 24 hours as dovish remarks from Fed Governor Waller reduced September hike odds from 70% to 50%, weakening the dollar and boosting risk assets.
  • Brent crude climbed toward $96 Friday, on track for a ~9% weekly gain. US strikes on Iran prompted retaliation against American bases and Hormuz vessels, with transits falling to 6 on Wednesday from an 11-day average near 13.
  • The Nasdaq 100 trades near 29,482, snapping a three-session losing streak after Fed Governor Waller signaled he'd support holding rates steady if inflation data cooperates. The 10-year Treasury yield retreated to 4.76% from near 4.80%, easing pressure on tech stocks.

Check more on zForex.com | Technical Outlook on Charts


US Payrolls Surprise Strongly >>> Keeping Fed Rate Hike Risk Alive

The latest U.S. jobs report came in much stronger than expected, with nonfarm payrolls rising by 162,000 versus forecasts near 55,000. July was also revised higher, easing some of the concerns around a sharp slowdown in the labor market.

The strong headline keeps pressure on the Fed to stay cautious on rates, especially with inflation data still ahead. For markets, the report is generally supportive for the U.S. dollar and Treasury yields, but the next CPI and PPI releases will likely be more important for the Fed’s September decision.
 

Strong US Jobs Lift Dollar, Pressure Metals (09.07.2026)

Global markets started the week with renewed focus on Federal Reserve tightening after stronger U.S. employment data lifted September rate-hike expectations.

Asia-Pacific tech shares rallied on hopes that a new OpenAI model could lift memory-chip demand. Japan’s Nikkei gained more than 2% and South Korea’s KOSPI over 3%, while strong US jobs data and higher oil prices kept rate concerns in play.

The dollar index held above 99 after US payrolls jumped 162,000 in August, well above the 56,000 forecast. Unemployment stayed at 4.1%, wage growth eased to 3.1%, and September Fed hike odds climbed to around 60% from 50%. US-Iran ship strikes and higher oil also supported the dollar.

Japan’s 10-year yield steadied around 2.91% as PM adviser Takuji Aida pointed to possible BOJ hikes in September and again by January. Takaichi’s expansionary fiscal policy has also pressured bonds, while an unusual GPIF meeting raised speculation that the $2 trillion fund could increase its domestic bond allocation.

After the strong jobs report, Thursday’s PPI and Friday’s CPI will provide the next test for Fed Chair Warsh’s hawkish stance. Oracle earnings will offer another look at AI financing and debt, with Adobe and Macy’s also reporting Thursday.

Economic Calendar​

eco-calendar-7-sept.jpg
  • EUR/USD trades near 1.1609, consolidating in a range as markets weigh dollar strength and shifting Fed-ECB rate expectations. The pair has faced pressure testing resistance near 1.1720, with support around 1.1650.
  • The Japanese yen held near 156 per dollar, extending last week's 2%+ gain on growing BOJ hike expectations. Japan's FX reserves dropped a record $79.6 billion in August after its largest-ever intervention, costing roughly $99 billion.
  • The British pound eased toward $1.35, hovering near a two-week low as strong US jobs data supported the dollar and heightened Fed rate-hike expectations. Meanwhile, UK markets fully price a Bank of England rate increase by year-end, following comments from BoE official Pill warning against delayed tightening.
  • The offshore yuan edged lower to around 6.71 per dollar, retreating from a three-year high as the PBOC signaled a more measured approach to appreciation. Chinese banks raised dollar deposit rates and supported Treasury purchases, while China injected CNY 300 billion into major banks and insurers in its biggest recapitalization in nearly two decades.
  • Gold fell toward $4,400, extending losses as solid US jobs data increased Fed hike expectations. September hike odds rose to roughly 60% from 50%. Gold also faced pressure from higher oil prices after US-Iran ship strikes stoked inflation concerns.
  • Silver slipped below $66 on Monday, deepening losses as solid US employment figures raised expectations for Federal Reserve policy tightening. Rising oil prices following maritime strikes between the US and Iran placed additional downward pressure on the metal by feeding inflation worries.
  • Bitcoin trades near $79,940, up 1.64% as buyers push toward the $80,000 resistance level. Dovish comments from Fed Governor Waller briefly lifted Bitcoin above $81,000 before a strong August jobs report revived rate-hike concerns.
  • Brent crude rose toward $97, extending gains as the US and Iran exchanged strikes in the Middle East. The US targeted three Iranian oil tankers over the weekend after Iranian missile attacks on US Navy warships, prompting Tehran to strike US-linked vessels and plan a "restricted" zone beyond Hormuz.
  • The Nasdaq 100 closed at 29,544, up 0.21%, though US markets are shut on Monday for Labor Day. Futures show a roughly 0.90% pullback to around 29,248 as traders digest recent economic data and Fed rate expectations.

Check more on zForex.com | Technical Outlook on Charts


Attached File(s)

  • eco-calendar-7-sept.jpg
    eco-calendar-7-sept.jpg
    16.5 KB · Views: 0
Last edited:

De-Dollarization Is More Concentrated Than It Looks

The US dollar’s share of global FX reserves has fallen to 57%, its lowest in at least 30 years and down 20 percentage points since 1999. However, much of the decline has been driven by China and, to a lesser extent, Russia.

The combined share of the dollar, euro, yen and pound has also dropped 12 points to around 87%. Yet between 2015 and 2023, roughly equal numbers of countries increased and reduced their dollar reserves.

This suggests de-dollarization is concentrated among a small group of reserve holders, while the dollar’s position in most portfolios remains relatively stable. Its global reserve currency status appears under limited threat for now.

De-Dollarization.jpg
 

Rate Hike Bets Increase as Oil Fuels Inflation Risks (09.08.2026)

Global markets remained focused on rising energy prices and expectations for further monetary tightening across major economies.

The dollar index slipped to around 98.8, falling for a second session as BOJ tightening bets and carry trade unwinding lifted the yen. Traders price in roughly 60% odds of a 25bp Fed hike next week after Friday’s strong jobs report, while this week’s inflation data and expected ECB tightening are next. US-Iran fighting also kept oil and inflation risks in play.

Japan’s 10-year yield fell to around 2.89% as the yen reached a seven-month high, easing inflation pressure. Carry trade unwinding, repatriation bets and US calls for tighter policy supported the currency, while a BOJ hike is expected this month and another could follow by January. Wages grew at their fastest pace since 1997, and Q2 GDP was revised higher.

The US 10-year yield held around 4.77% before this week’s inflation data. August payrolls rose 162K, well above forecasts, with earlier months revised higher, pushing odds of a 25bp Fed hike to roughly 60%. Expected ECB and BOJ tightening and higher oil prices added to rate pressure.

US stock futures edged lower as trading resumed after the holiday weekend. Oil extended gains following weekend US-Iran strikes, while Canada’s retaliatory tariffs on $20 billion of US goods took effect. Fed hike odds stood near 60%, as Uber prepared a euro bond debut and Novo Nordisk halted two more heart-drug trials.
  • The euro held just above $1.16 as traders assessed the AfD’s Saxony-Anhalt victory and Thursday’s ECB decision, while higher oil added to inflation concerns. The AfD secured 44% of the vote, dealing a setback to Chancellor Merz’s conservatives. An ECB hike on Thursday is priced in, with roughly 90% odds of another by year-end.
  • The yen strengthened past 154 per dollar, its strongest level since February, extending its recovery after hitting a 40-year low in July. A BOJ hike is expected this month, with an adviser signaling another could follow by January as Takaichi’s administration becomes more open to tightening. Wages also rose at their fastest pace since 1997.
  • GBP/USD consolidated near 1.3540, establishing higher lows as UK Finance Minister Healey's fiscal discipline pledge helped stabilize government bond yields near 5.15%. Although strong US jobs data initially supported the dollar, dollar momentum slowed following hawkish remarks from the Bank of England's chief economist, with investors now anticipating up to two British rate increases over the next six months.
  • The offshore yuan held around 6.7100 per dollar, near its strongest level since January 2023, supported by strong Chinese trade figures. Exports jumped 25.0% year-on-year to $401.44 billion in August, while imports surged 28.2% and the trade surplus widened to $119.09 billion.
  • Gold traded near $4,430 as expectations for rate hikes from major central banks and higher oil prices weighed on the metal. Traders price in roughly 60% odds of a Fed hike next week, while the ECB and BOJ are also expected to tighten.
  • Silver climbed above $66 on Tuesday, though gains remained capped as traders prepared for potential interest rate increases from global central banks responding to oil-driven inflation. Markets currently price in a 60% probability of a Fed rate hike next week, with tightening also anticipated from the ECB and BOJ. Sustained US-Iran tensions keep energy prices elevated, offering continuous structural support for precious metals.
  • Brent held above $97, near six-week highs, after Iran said an Oman agreement on managing Hormuz shipping was close to completion, raising questions over Tehran’s growing control of the waterway. Attention also turns to the US response following weekend strikes on Iranian tankers. Oil gained nearly 10% last week, while Aramco’s Jazan facility was hit Monday.
  • The Nasdaq 100 traded near 29,670, consolidating below the 30,000 threshold as strong AI infrastructure demand competes with higher Fed rate expectations. Semiconductor and AI stocks continue to provide support, while the prospect of tighter policy puts pressure on growth-heavy tech valuations.
  • Bitcoin traded near $79,000, consolidating after meeting resistance around $80,000 to $83,000. Futures open interest of roughly $27.5 billion is running ahead of softer spot demand, while more than $200 million in long positions were recently liquidated.

Check more on zForex.com | Technical Outlook on Charts

 
SpaceX could see a wave of passive buying in the upcoming quarterly Nasdaq 100 rebalancing.

More than 1 billion shares have been released from lockup restrictions, lifting the company’s free float to around 30%. This could raise SpaceX’s Nasdaq 100 weighting from 1.25% to roughly 2.25%, with JPMorgan estimating around $15.5 billion in forced buying from index funds and ETFs tracking the benchmark.

SpaceX shares have traded mostly between $133 and $150 in recent weeks. The rebalancing could support the stock in the near term, though another 1.3 billion shares are set to unlock after the November earnings report, potentially adding selling pressure later.

Nvidia leads the Magnificent 7 in 2026, up 23.5% through Sept. 4, followed by Microsoft (17.7%) and Amazon (12%). Tesla sits at the bottom, down 21.3%.

mag7-stocks.png
 

Markets Brace for ECB Decision (09.09.2026)

Rising energy prices and tighter policy expectations remain key market drivers as Middle East tensions continue to support commodities. Gold is hovering near $4,400, Bitcoin around $79,000, while the US 100 has softened and the euro is holding near $1.1630 ahead of the ECB decision.

Attention will then shift to US PPI on Thursday and CPI on Friday, both of which could reshape expectations for next week’s Fed meeting. Meanwhile, the yen has strengthened toward 153 per dollar as BOJ tightening bets, short covering and capital repatriation fuel a broader carry-trade unwind.

Economic Calendar​

eco-calendar-9-sept.jpg
  • The euro traded around 1.1630 as attention turned to Thursday’s ECB decision, with higher oil prices adding to inflation pressure. A rate hike is expected this week, while another increase by year-end is priced in with near certainty.
  • The yen strengthened toward 153 per dollar, staying close to a seven-month high after US Treasury Secretary Scott Bessent warned against shorting the currency. The former hedge fund manager said he has “pretty good insight” into the BOJ’s likely moves when assessing the yen and possible intervention.
  • The British pound traded stably just above $1.35 as persistent inflation worries strengthened expectations for additional Bank of England rate increases. Energy markets experienced sharp gains, with Brent crude nearing $100 per barrel and UK natural gas reaching multi-year highs.
  • The offshore yuan traded near 6.70 per dollar, its strongest level since January 2023, as it gained appeal as a funding currency for carry trades. Recent yen strength has encouraged a shift toward alternatives such as the yuan, helped by China’s relatively low interest rates and currency stability.
  • Gold struggled near $4,400 as higher oil prices strengthened expectations that major central banks could raise rates this month. The probability of a Fed hike next week is around 60%, while the ECB and BOJ are also expected to tighten.
  • Silver traded near $66.6 an ounce on Wednesday following two sessions of decline, as elevated energy costs heightened inflation concerns and reinforced expectations for additional rate hikes.
  • Bitcoin traded at $78,669, up 0.29% from the previous session. The cryptocurrency has gained 23.09% over the past month but is still down 30.98% year-on-year. Forecasts point to $80,762 by quarter-end and $90,339 within a year.
  • Brent climbed above $99 a barrel, its highest level in nearly seven weeks and close to the $100 mark, after the US targeted several Iranian tankers near Kharg Island, a major oil export hub. The attacks raised concerns over possible disruptions to global oil supplies.

Check more on zForex.com | Technical Outlook on Charts


Euro Gains Ahead of ECB Decision (09.10.2026)

Europe could get another rate hike today, as higher oil prices make the ECB’s inflation challenge harder. A further increase by year-end is priced in with near certainty, even as policymakers stick to a data-dependent path.

US PPI is due later today, followed by CPI on Friday, putting the Fed outlook back in play. Gold is holding near $4,400, while the US 100 has slipped 0.29% to 29,258 as rate uncertainty weighs on tech.

Brent is holding near $101, close to its highest since May, as the US-Iran conflict raises the risk of further supply disruptions. Higher oil prices add another inflation challenge as major central banks consider tighter policy.

Economic Calendar​


eco-calendar-10-sept.jpg
  • The euro edged up to 1.164, its highest since late August, before Thursday’s ECB policy decision. A rate hike is expected by many, with policymakers likely to maintain a data-dependent stance as the conflict involving Iran fails to clear the air for the inflation outlook.
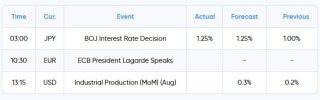
  • The yen traded around 153.4 per dollar, close to a seven-month high as expectations build for a BOJ rate hike next week. The central bank is predicted to raise its policy rate to 1.25%, the highest in about 31 years, following its June increase.
  • The British pound rose toward $1.354, sustained by expanding expectations that the Bank of England will pursue additional interest rate increases to counter mounting inflation.
  • The offshore yuan held near 6.7063 per dollar, its strongest level since early 2023, as demand for the currency as a carry-trade funding option grew. With the yen strengthening sharply, the yuan has gained appeal as an alternative due to China’s low interest rates and relatively stable currency.
  • Gold traded around $4,400 per ounce, holding recent gains before key US inflation releases that could shape the Fed outlook. August PPI is due later today, followed by the latest consumer inflation data on Friday.
  • Silver traded above $67 per ounce on Thursday, maintaining recent gains while investors focused on key US inflation reports that could shape future Federal Reserve policy. The August producer price index arrives later today, followed by consumer inflation figures scheduled for release on Friday.
  • Bitcoin traded at $78,402, up 0.18% from the previous session. The cryptocurrency has gained 23.37% over the past month but is still 32.14% lower year-on-year. Forecasts point to $80,762 by quarter-end and $90,339 within a year.
  • Brent held around $101 a barrel, close to its highest level since May, as US-Iran tensions raised the risk of further Middle East supply disruptions. Tehran said it was prepared to intensify the conflict, challenge the US naval blockade and increase attacks if US forces continue targeting Iranian territory.
  • Nasdaq fell 86 points to 29,258. The index has declined 0.91% over the past four weeks but is still up 21.95% over the past 12 months. Forecasts point to 28,915 by quarter-end and 27,106 within a year.

Check more on zForex.com | Technical Outlook on Charts


Fed Hike Debate: Inflation Is More Than Demand

The Fed faces another difficult decision as August CPI approaches. Markets increasingly expect another hike, but inflation is being driven by more than strong demand.

Higher energy prices, tariffs, and AI-related technology and infrastructure demand are adding price pressure. Higher rates cannot increase oil supply, reverse tariffs, or solve semiconductor shortages. Instead, they mainly weaken housing, consumption, and investment.

A hot CPI reading could strengthen the higher-for-longer outlook, lift Treasury yields, pressure risk assets, and increase volatility in gold and the dollar.

To summarize, Friday's CPI could strengthen the case for another Fed hike.

Fed-rate-hike.png
 

Hot US Inflation and Oil Pressure Markets (09.11.2026)

Inflation and interest rate expectations took center stage as surging energy costs and stronger U.S. producer prices reshaped the policy outlook. The dollar index held above 99 as surprisingly hotter U.S. producer inflation pushed Fed rate hike odds to 71%.

US stock futures were little changed Friday after the Dow, S&P 500 and Nasdaq fell for a fourth straight session on higher oil and Treasury yields. August CPI is next after stronger producer inflation, driven by Iran war energy costs, pushed Fed hike odds to 71%. Oracle gained more than 4% after hours on strong earnings, while Adobe fell over 2% on weak guidance.

The dollar stayed above 99 before CPI, supported by stronger Fed hike expectations and rising Treasury yields. Oil surged past $100 as the US-Iran conflict showed no signs of easing, raising the risk of prolonged supply disruptions and further inflation pressure.

The US 10-year yield reached 4.97%, its highest since 2023, after a $5.2 billion Treasury buyback fell short of the $6 billion cap. Hot August PPI and oil above $100 added to the selloff, reinforcing the 71% probability of a Fed hike.

Japan’s 10-year yield climbed to 2.99%, near 30-year highs, tracking the US bond selloff as higher oil added another inflation risk. Japanese PPI rose 7.6%, while manufacturer sentiment reached its strongest since Q4 2021, reinforcing BOJ hike expectations after Masu signaled further tightening.

Economic Calendar​

eco-calendar-11-sept.jpg
  • The euro slipped toward 1.16 after the ECB delivered its second hike since the US-Iran war began and raised its inflation and growth forecasts. The dollar held firm after strong US PPI pushed Fed hike odds above 70%.
  • The yen weakened past 154 per dollar, retreating from near seven-month highs as US PPI strengthened the dollar and raised Fed hike bets. The yen is still up more than 3% this month, supported by rate bets, carry trade unwinding and capital repatriation.
  • The British pound declined to 1.3510, pressured by growing policy divergence. Strong US producer price data lifted Federal Reserve rate hike expectations, while Bank of England leadership signaled caution. Brent crude exceeding $105 amid Middle East supply disruptions further strained the UK economy.
  • USD/CNY traded near 6.7112, close to a nearly one-year low, as the yuan held firm despite surging US Treasury yields that typically support the dollar. The PBOC set its reference rate at 6.7743, balancing import inflation against export competitiveness.
  • Gold traded near $4,400 an ounce after falling around 2%, with CPI next in line to test Fed hike expectations after hotter PPI lifted the odds to 71%. Bullion is heading for a third straight weekly decline, down more than 2%.
  • Silver traded near $64 on Friday after dropping over 5% in the previous session, as traders awaited incoming US consumer inflation data. Stronger producer price figures recently pushed Fed rate hike probabilities to 71%.
  • Bitcoin traded near $76,811 after touching an intraday low of $76,676, as oil above $100 and surging US Treasury yields strengthened expectations for a Fed hike. Strong PPI and today’s CPI release have pushed hike odds to 60–76%, weighing on crypto despite $3.8 billion of spot Bitcoin ETF inflows over the past three weeks.
  • Brent climbed above $108, up around 12% this week and heading for its biggest weekly gain since mid-July as the US-Iran conflict intensified. Officials reportedly warned Trump that the war could last through his term, while Iran signaled its intention to keep fighting and claimed to have rebuilt its missile capacity.
  • The Nasdaq 100 fell 1.08% to 29,103.51, extending its losing streak to four sessions as oil above $100 and Treasury yields at multiyear highs pressured tech and growth stocks.

Check more on zForex.com | Technical Outlook on Charts


Eyes on Fed Amid Rising Energy Costs (09.14.2026)

The ECB delivered a 25-basis-point hike, lifting its deposit rate to 2.50%, while EUR/USD stayed trapped around 1.1590. In Japan, producer inflation accelerated 7.6% in August, strengthening expectations for a BOJ hike this month even as the yen pulled back beyond 154 per dollar.

Wednesday’s Fed decision dominates the week after August CPI held at 3.4% annually but rose 0.4% monthly, the strongest increase in three months. Traders now price an 86% chance of a 25-basis-point hike, keeping pressure on gold near $4,300 and contributing to four straight losses for the Nasdaq 100.

Brent approached a four-month high near $108 after gaining more than 9% last week, as Saudi Arabia suspended its 7 million-barrel-per-day East-West pipeline following drone attacks. Talks over a temporary Hormuz shipping corridor were also postponed, adding another complication to regional energy flows.

The offshore yuan traded near 6.70 per dollar, its strongest since January 2023, as the yen’s rally encouraged carry traders to look toward China’s lower borrowing costs. Chinese inflation also accelerated, with CPI at 0.8% and producer inflation at 3.8%, as higher energy costs fed into domestic prices.

Economic Calendar​

eco-calendar-14-sept.jpg
  • EUR/USD hovered around 1.1590, extending its range-bound trade into a third week and staying within roughly 100 pips for a second consecutive week before Wednesday’s Fed decision.
  • The yen weakened past 154 per dollar, pulling back from near seven-month highs as accelerating US producer inflation strengthened the dollar and Fed hike expectations.
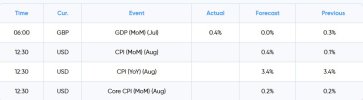
  • GBP/USD pair struggled to hold modest early gains on Monday, consolidating around the 1.3520 level while staying above weekly lows. Sterling drew initial support from surprisingly strong UK GDP data, which revealed 0.4% economic expansion in July against forecasts of flat growth
  • USD/CNY traded near 6.70 per dollar, close to its strongest level since January 2023, as the yen’s recent surge encouraged greater use of the Chinese currency as an alternative for carry-trade funding.
  • Gold stayed near $4,300 an ounce after three straight weekly declines, pressured by higher oil and expectations for tighter Fed policy.
  • Silver traded near $63.5 per ounce after dropping more than 5% on Thursday, as market participants awaited key CPI figures. Higher producer price data previously pushed Fed rate hike probabilities to 71%.
  • Bitcoin traded near $77,488, gaining 0.90% from the previous session. The cryptocurrency is up 22.95% over the past four weeks but down 32.88% over 12 months.
  • Brent climbed toward $108 a barrel, its highest in four months, after gaining more than 9% last week as Saudi Arabia suspended the East-West pipeline following drone attacks. The 7 million-barrel-per-day route, used to bypass the Strait of Hormuz and carry crude to Red Sea ports, has no clear reopening date.
  • Nasdaq 100 fell 1.08% to 29,103.51, marking a fourth straight decline as oil above $100 and Treasury yields at multiyear highs weighed on tech and growth stocks.

Check more on zForex.com | Technical Outlook on Charts


Dollar Strengthens as Markets Brace for Fed (09.15.2026)

Central bank policy takes center stage as investors prepare for a series of major rate decisions this week.

A 25bp Fed hike on Wednesday is now priced at around 92%, with oil above $100 and the US 10-year yield approaching 5%, reinforcing inflation concerns. The dollar strengthened, pushing the euro toward $1.15 and the yen toward 155.

The ECB has already hiked and at least one more increase is priced this year. The BoE is expected to hold Thursday in a close decision, while the BOJ could raise rates to 1.25% Friday, the highest since April 1995.

Chinese fixed-asset investment fell 7.2%, retail sales growth slowed to 0.4%, and unemployment rose to 5.3%. Industrial output improved to 5.2%, while the decline in house prices eased to 3%, leaving pressure on Beijing to add support as growth risks missing the 4.5%–5.0% target again.

Economic Calendar​

eco-calendar-15-sept.jpg
  • The euro slipped toward $1.15, its weakest since mid-August, as the dollar strengthened before an expected Fed hike on Wednesday. The ECB, which hiked last week, signaled more tightening, with at least one additional increase priced this year.
  • The yen weakened toward 155 per dollar for a second session as the dollar gained before the expected Fed hike and higher oil raised Japan’s import costs. The BOJ is expected to raise its policy rate to 1.25% Friday, the highest since April 1995, with another hike later this year also possible.
  • The British pound fell below $1.35, its weakest since mid-August, as the dollar strengthened ahead of Wednesday’s expected Fed rate hike. The BoE is expected to hold rates at 3.75% on Thursday, although rising oil prices have increased inflation concerns. Goldman Sachs expects a 25-basis-point hike in November, supported by persistent inflation and resilient UK growth.
  • The offshore yuan held near 6.71 per dollar, retreating from a three-year-plus high as Chinese data sent mixed signals. Fixed-asset investment fell 7.2% in January–August, the sharpest drop for the period since January–April 2020
  • Gold hovered near $4,300, close to a five-week low, as high oil prices strengthened Fed hike expectations.
  • Silver traded near $63 per ounce, close to a five-week low as elevated oil prices reinforced expectations for tighter Fed policy. Markets now price around a 92% chance of a 25-basis-point hike on Wednesday. Continued disruption to Saudi Arabia’s East-West pipeline kept energy prices elevated, while the 10-year Treasury yield approached 5%, adding pressure on silver.
  • Bitcoin traded at $77,814, down 0.44%. It has fallen 23.86% over four weeks and 33.40% over 12 months. Trading Economics models and analyst expectations point to $77,811 by quarter-end and $87,311 in one year.
  • Brent approached $107 a barrel as supply concerns persisted. Saudi Arabia’s drone-damaged East-West pipeline, which bypasses Hormuz, remained closed with no restart date, while Iran-Gulf talks over the strait were shelved.
  • Nasdaq 100 fell 0.82%, to 29,088. It is down 3.03% over four weeks but remains 19.83% higher over 12 months. Trading Economics models and analyst estimates project 28,740 by quarter-end and 26,934 in one year.

Check more on zForex.com | Technical Outlook on Charts


Euro Area Job Vacancies Decline

The euro area job vacancy rate fell to 2.1% in Q2 2026, down from 2.3% in the previous quarter, pointing to softer hiring demand. The EU rate also declined to 2.0%, suggesting businesses are becoming more cautious about adding workers.

Fewer vacancies could gradually reduce wage pressure and support the disinflation trend. If the slowdown continues, it may become another factor for policymakers to consider when assessing the outlook for growth and future interest-rate decisions.

euro-job-vacancy-rates.png
 

Gold and Silver Rebounds Ahead of Fed (09.16.2026)

The Fed is expected to raise rates 25bp Wednesday, its first hike in roughly three years, as $100-plus oil keeps inflation pressure alive. The BoE is likely to hold Thursday, while markets put the chance of a BoJ hike Friday near 80%. The ECB has already moved, with at least one more hike priced this year.

Brent slipped below $108 after US crude inventories unexpectedly jumped 7.14 million barrels, but Gulf supply disruptions continue to support prices. Saudi loadings remain suspended at Yanbu, while Libya has halted two fields and a pumping station.

Fed expectations have strengthened the dollar, sending the euro toward $1.15, its lowest since mid-August, and pushing the yen beyond 155. For the yen, Friday’s potential BoJ hike could become the next major test.

China’s fixed-asset investment fell 7.2%, retail sales growth slowed to 0.4%, and unemployment rose to 5.3%. Industrial production moved the other way, accelerating to 5.2%, leaving pressure on Beijing to do more as growth risks missing its 4.5%-5.0% target.

Economic Calendar​

eco-calendar-16-sept.jpg
  • The euro eased toward $1.15, its weakest level since mid-August, as the dollar stayed firm before Wednesday’s widely expected Fed rate hike. Pressure also came from oil, with six months of US-Israeli conflict with Iran pushing crude well above $100 and keeping inflation high.
  • The yen weakened beyond 155 per dollar, extending its decline for a third session as the dollar strengthened before the expected Fed hike. Higher oil prices added another headwind for Japan, which relies heavily on energy imports.
  • The British Pound fell below $1.35, touching its lowest level since early August. Stronger U.S. Dollar demand ahead of an expected Federal Reserve rate hike pressured the currency, while the Bank of England is anticipated to maintain rates at 3.75% on Thursday
  • The offshore yuan traded around 6.71 per dollar as Chinese data pointed in different directions. Fixed-asset investment fell 7.2% in January-August, retail sales growth slowed to 0.4%, and unemployment rose to 5.3%.
  • Gold climbed back above $4,300 an ounce, snapping a two-day decline as some of the recent pressure from oil and bond yields faded. Focus now shifts firmly to the Fed, which is expected to deliver a 25-basis-point increase, its first hike in roughly three years, as it tries to contain inflation.
  • Silver advanced above $64 an ounce on Wednesday, gaining for a second consecutive session as momentum in oil prices and bond yields cooled ahead of key central bank decisions. Crude pulled back from multi-month highs following an unexpected U.S. inventory surplus, though ongoing Middle East disruptions limited downside.
  • Bitcoin traded at $77,814, down 0.44%, from the previous session. The latest decline adds to a difficult stretch for the cryptocurrency, which has lost 23.86% over the past four weeks and 33.40% over the past 12 months.
  • Brent slipped below $108 a barrel, pulling back from four-month highs after an unexpected surge in US crude inventories challenged the recent upward move. API data showed stocks rising by 7.14 million barrels last week, reversing the previous 300,000-barrel draw and defying expectations for another decline.
  • The Nasdaq 100 traded at 29,010, down 0.65%, from the previous close. The index has now fallen 3.29% over the past month, although it remains 19.76% higher over the past year.

Check more on zForex.com | Technical Outlook on Charts


Wall Street Has a New Fear: The Bond Market

Wall Street’s attention is shifting toward the bond market as long-term US borrowing costs climb into territory not seen for nearly two decades. Bank of America’s September Fund Manager Survey identified a disorderly rise in government bond yields as the leading tail risk, with the US 10-year Treasury yield now above 5%, its highest level since 2007.

image (23).png

The surge has also cast doubt on how much relief can come from larger Treasury buybacks. The program is designed to improve liquidity and trading conditions, but fund managers largely question its ability to bring yields down. In the BofA survey, 46% said buybacks would have no meaningful effect on Treasury yields, while 29% said the measures could fail to contain rising borrowing costs. Just 16% expect them to produce a sustained decline in long-term yields.

Pressure Goes Beyond Liquidity

uybacks may help the Treasury market function more smoothly, but the forces pushing yields higher run deeper. Persistent inflation concerns are being compounded by heavy government borrowing, uncertainty over the fiscal outlook and higher term premiums, all of which have added pressure to longer-dated debt.

Fund positioning reflects that unease. Managers were a net 48% underweight bonds in September, the most bearish allocation since May 2022. They have now maintained an underweight position for 17 consecutive months, according to BofA, showing that the rise in yields has yet to generate a broad return to government debt.

image (24).png

Is 6% the Level That Brings Buyers Back?

For a significant group of fund managers, current yields still do not offer enough incentive to move money out of equities. More than a quarter of respondents said they would need more attractive levels before making a substantial rotation into government bonds, with a US long-bond yield of around 6% cited as one potential threshold.

A further rise in yields could eventually make bonds attractive enough to draw buyers back, but reaching those levels would come with consequences elsewhere. Equities could face additional pressure, companies would encounter higher financing costs, mortgages could become more expensive, and the US government would have to absorb an even larger interest burden on its debt.
 

Fed Rate Hike Strengthens Dollar (09.17.2026)

Brent fell toward $105.50 as Saudi Arabia said around half of its East-West pipeline capacity could return within days, with full operations targeted within six weeks. Meanwhile, 18 million barrels of crude and petroleum products moved through Hormuz earlier this week.

The Fed delivered its first rate hike in three years, lifting rates 25bp to 3.75%–4% and leaving another increase on the table before year-end. The dollar strengthened after the decision, pushing EUR/USD toward 1.1460 and USD/JPY above 156.

Economic Calendar​

eco-calendar-17-sept.jpg
  • EUR/USD fell toward 1.1460 during Asian trading as the dollar strengthened after the Fed delivered its first rate hike in three years. With the policy decision now absorbed, attention shifts to US Initial Jobless Claims later Thursday for the next signal on the US economy.
  • The yen traded around 156.1 per dollar after three straight declines, pressured by a stronger dollar following the Fed’s first hike in three years and its signal of further tightening this year. The BOJ is expected to raise rates Friday, with another increase projected by the end of January.
  • The British pound dropped under $1.35, hitting its lowest mark since early August. Strong demand for the US dollar ahead of a Federal Reserve rate increase weighed on the currency, while the Bank of England is expected to keep rates steady at 3.75%. Although recent figures revealed the strongest UK economic expansion in 18 months, surging oil costs from Middle East tensions complicate the inflation outlook, keeping investors focused on a potential November rate rise.
  • The yuan strengthened slightly toward 6.70 per dollar as Beijing took another step toward expanding its international use. On September 14, the Shanghai Clearing House launched central counterparty clearing for spot trades in the Singapore dollar, New Zealand dollar and Thai baht, with 12 banks clearing 996 million yuan ($148 million) in the first session.
  • Gold recovered toward $4,300 an ounce as easing oil prices offered some relief after the previous session’s losses. Still, the Fed’s 25bp hike to 3.75%-4% kept pressure on bullion, with another increase possible before year-end. Chair Kevin Warsh pointed to persistent inflation after US core inflation rose more than expected in August.
  • Silver rose toward $63.80 per ounce on Thursday, recovering from earlier weakness as lower oil prices eased some inflation concerns and supported precious metals. However, upside remains constrained after the Federal Reserve raised rates by 25 basis points and signaled another potential hike this year.
  • Bitcoin traded at $76,317, gaining $169 from the previous session. The cryptocurrency is up 17.98% over the past four weeks but down 34.86% over 12 months. Trading Economics models and analyst expectations point to $77,811 by quarter-end and $87,311 in one year.
  • Brent traded near $105.50 a barrel after a sharp decline, as Saudi Arabia’s plans to restore its East-West pipeline eased supply concerns. Around half of its capacity could return within days and full operations within six weeks after last week’s drone attacks, while Saudi Arabia is moving more crude through Hormuz with US military assistance.
  • The Nasdaq 100 traded at 29,152, up 0.03% from the previous session. The index has gained 1.15% over four weeks and 19.21% over 12 months. Trading Economics models and analyst expectations project 28,740 by quarter-end and 26,934 in one year.

Check more on zForex.com | Technical Outlook on Charts


Fed Hike Sets the Tone for Markets (09.18.2026)

The Fed delivered its first rate increase since July 2023, unanimously lifting the target range to 3.75%–4.00% and leaving another hike possible before year-end.

Bank of England left rates unchanged but kept the possibility of further tightening open.

Economic Calendar​


eco-calendar-18-sepy.jpg
  • The euro traded slightly under $1.15, staying around its lowest level since the end of July after the Federal Reserve increased interest rates and indicated the possibility of another hike before year-end. US policymakers unanimously raised the federal funds target range to 3.75%-4%, the first increase since July 2023.
  • The yen slipped past 156 against the US dollar on Friday and hovered close to its weakest level in two weeks. Investor attention is on the upcoming Bank of Japan policy announcement, with expectations firmly tilted toward a rate hike.
  • The British pound remained under $1.34, lingering near its lowest level since late July after the Bank of England held interest rates at 3.75% in a 6-3 vote. Central bank officials signaled that further monetary tightening might become necessary if escalating Middle East conflict sparks a fresh wave of inflationary pressure.
  • The offshore yuan strengthened slightly to approximately 6.69 against the US dollar on Friday, following a stable session previously. China’s ongoing expansion of currency-clearing arrangements reflects its efforts to increase the yuan’s role in international transactions and further advance its global internationalization.
  • Gold hovered around $4,380 per ounce, following a nearly 2% increase in the prior trading session. Lower oil prices helped reduce inflationary pressures, while the resulting decline in bond yields provided additional support for gold prices.
  • Silver traded above $66.6 an ounce on Friday following a 3% surge in the prior session. Falling oil prices helped ease inflation worries and lower bond yields, creating a supportive backdrop for non-yielding precious metals as market sentiment improved.
  • Brent crude fell toward $104 per barrel, extending its losses for a third straight session. The decline came as concerns over potential supply disruptions in the Middle East eased, while expectations increased that diplomatic efforts could help end the conflict and restore energy supplies.
  • Bitcoin traded at 76,578, rising 0.22% from the previous session. Over the past four weeks, Bitcoin has gained 10.65%, while its price remains 33.81% lower than a year ago.
  • Nasdaq 100 traded at 29,386, rising 502 points from the previous session. Since last month, the index has gained 0.13%, while its price has increased 19.33% over the last 12 months.

Check more on zForex.com | Technical Outlook on Charts